Comrade Ho Thi Nguyen Thao, Member of the Provincial Party Standing Committee, PPC Standing Vice Chairwoman and Head of the Provincial Representative Board of the Viet Nam Bank for Social Policies (VBSP) Board of Directors, recently chaired a meeting to review social policy credit operations over the first nine months of 2026 as well as discuss tasks for the remainder of the year.
During the first nine months of 2026, the VBSP Dak Lak Branch closely followed directives from central and provincial authorities, effectively implementing policy credit programmes while continuing to serve as an important pillar of social welfare and sustainable poverty reduction.
As of September 30, 2026, total policy credit resources exceeded 16.128 trillion VND, up 11.26% from 2025, including more than 1.626 trillion VND in entrusted funds from local budgets. Total outstanding loans under credit programmes exceeded 16.081 trillion VND, serving 247,535 borrowers holding outstanding loans. The growth rate reached 11.27%, surpassing the national average.
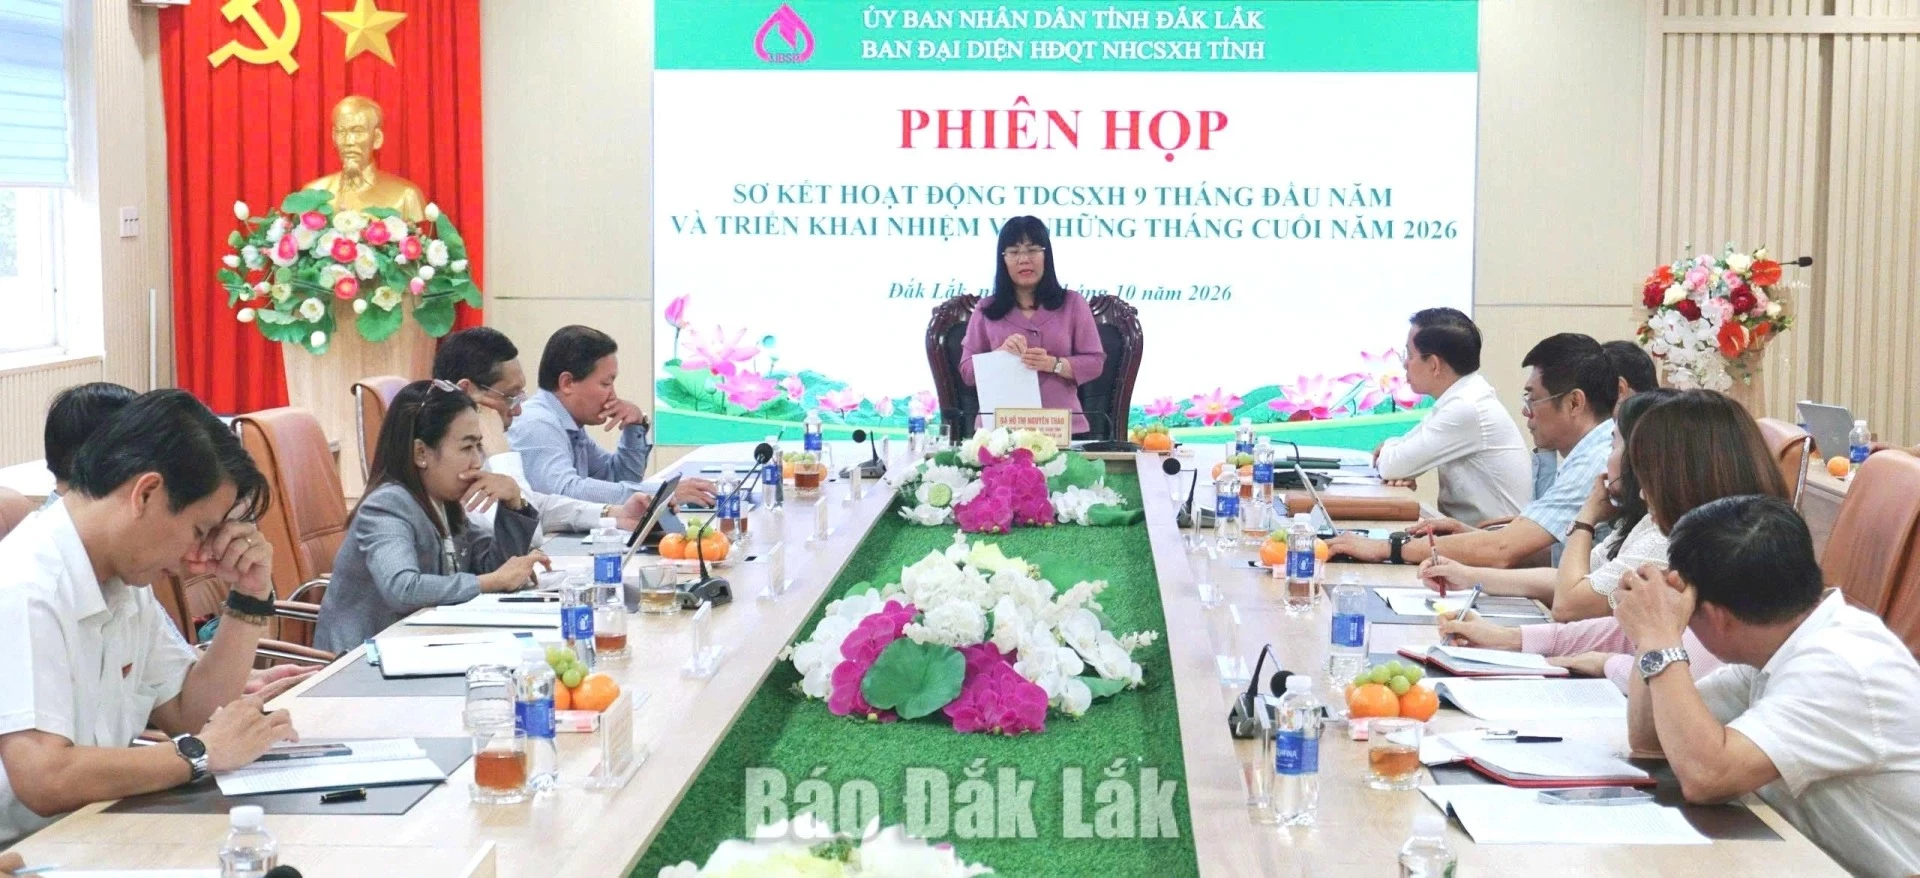 |
| Comrade Ho Thi Nguyen Thao, Member of the Provincial Party Standing Committee, Standing Vice Chairwoman of the Provincial People’s Committee and Head of the Provincial Representative Board of the VBSP Board of Directors, addressing the meeting. |
The funds supported 16,400 poor, near-poor and newly escaped-poverty households, along with more than 11,700 households in disadvantaged areas; created jobs for more than 16,900 workers; supported more than 3,500 pupils and students; and financed the construction of numerous clean water and environmental sanitation facilities as well as social housing projects province-wide.
Concluding the meeting, comrade Ho Thi Nguyen Thao asked that the provincial VBSP branch focus on fulfilling 100% of its assigned capital allocation targets by October 30, 2026. The branch was also tasked with coordinating with the Department of Finance to advise the PPC on submitting to the Provincial People’s Council a proposal to allocate 440 billion VND in locally entrusted capital, while stepping up deposit mobilisation among organisations and individuals to increase lending resources. In addition, the branch must strengthen operational security, strictly control the ratio of overdue alongside frozen loans below 0.2%, focus on settling loans falling due at year-end, and improve the effectiveness of savings coupled with credit groups.
Translated by KHUONG THAO